Tax on incentives: A compliance guide for research programs
By Russ Rizzo●6 min. read●Oct 26, 2026
Are incentives taxable? Yes. The IRS treats any compensation you give a research participant as taxable income, whether that's cash, a cash equivalent like a gift card or prepaid Visa card, or anything else of monetary value.
What varies is your side of it: which forms you collect, whether you withhold anything, and what you file. That depends on how much you've paid the participant and where they live.
Here's what U.S.-based research teams need to know about tax on incentives:
When and how to report payments
What paperwork to file
When you might have to withhold taxes
What penalties you could face if you get it wrong
DISCLAIMER: This is not tax advice.
What is the IRS reporting threshold for U.S. research participants?
For research participants in the U.S., you're required to report once someone receives $2,000 or more in a calendar year from your company.
That number changed recently. Through 2025, the threshold was $600. The One Big Beautiful Bill Act raised it to $2,000 for payments made on or after January 1, 2026, and starting in 2027 it'll be adjusted annually for inflation and rounded to the nearest $100.
The higher threshold means fewer participants will trigger a filing requirement. High-frequency panelists and people in longitudinal studies still can, especially as incentive payments continue to increase.
Once a participant crosses that line, you need to do two things to stay on the right side of the IRS:
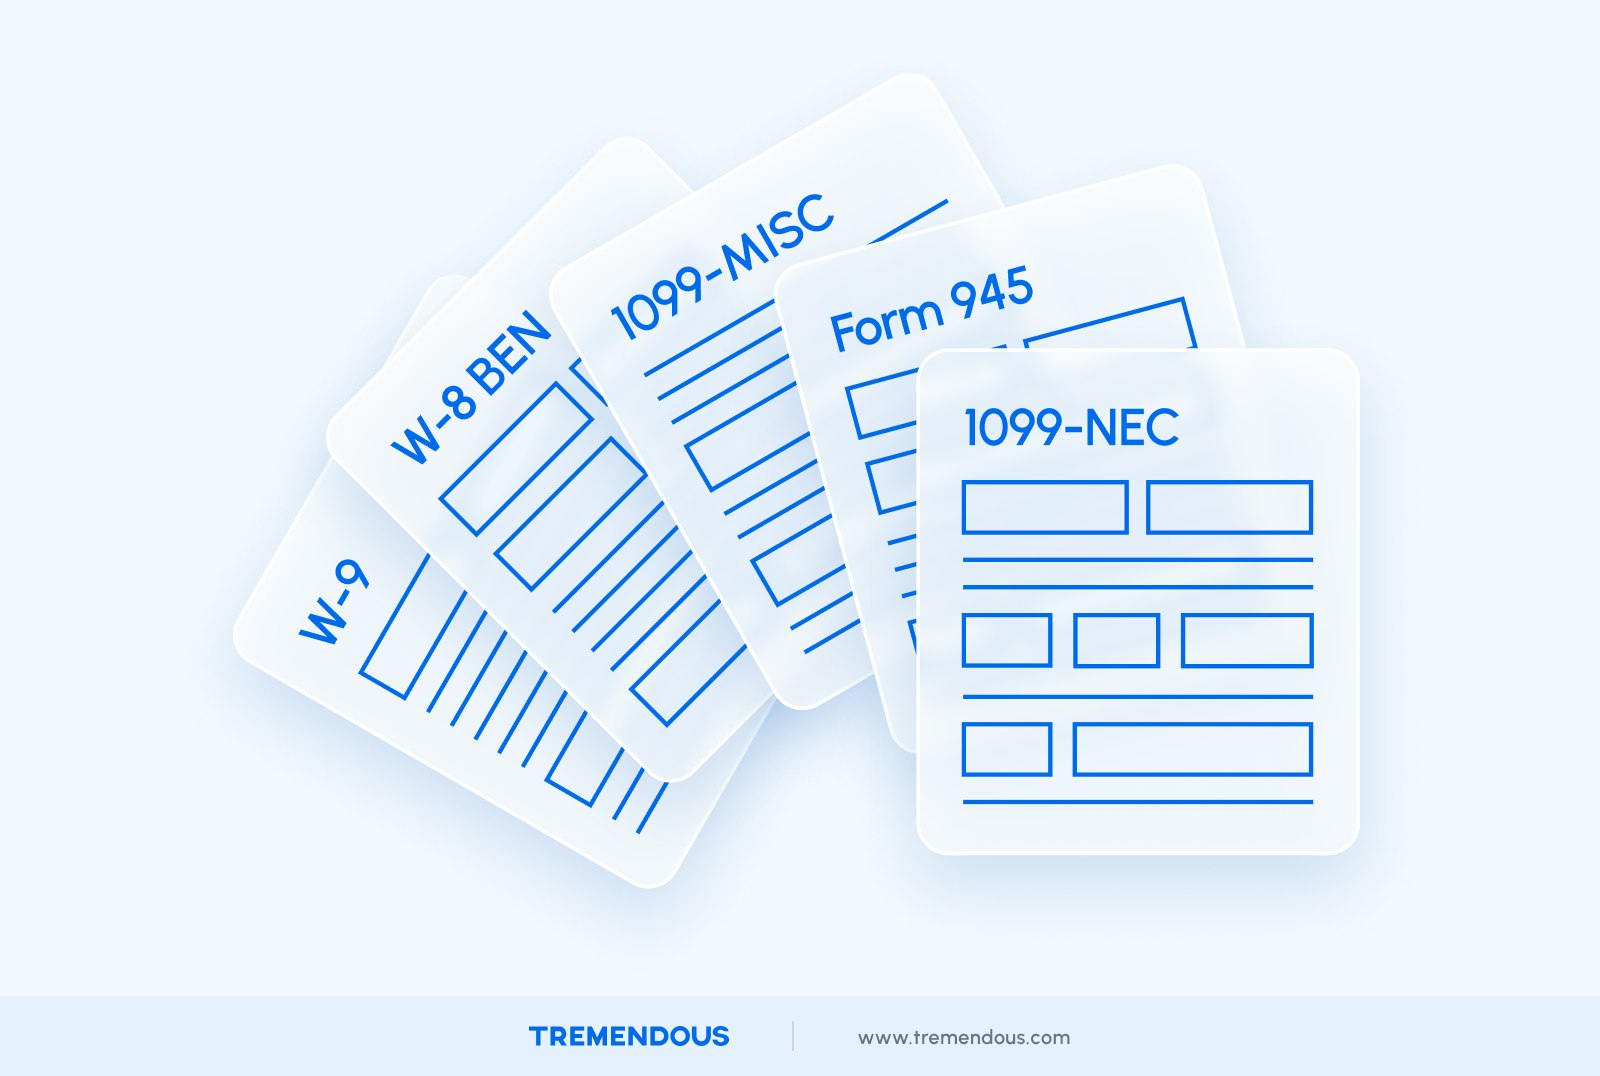
Before tax season, request a W-9 ("Request for Taxpayer Identification Number and Certification") from the participant. This form includes the person's tax identification number or social security number, plus the other information you'll need to report their payments when you file.
During tax season, file a 1099-MISC ("Miscellaneous Information") along with your other tax paperwork, the same way you would for a freelancer or contract worker.
You aren't required to withhold taxes from participants in the U.S. who provide a W-9. You just report what you paid them.
For U.S. citizens and permanent residents earning less than $2,000 from your company in a calendar year, there's no requirement to request a tax form or report the payments. That doesn't make the incentive tax-free for the participant, though. They still owe tax on what they receive, and the threshold only determines your reporting obligation.
How are incentive payments to non-U.S. participants taxed?
Payments to participants outside the U.S. can raise different tax form, withholding, and reporting questions depending on the participant's status and where the activity takes place. Check with your tax advisor before launching an international study.
Tracking payments
Research institutions issue their own guidelines for what information researchers should collect at the start of a study (examples: University of Dayton, Vanderbilt University, University of Vermont, University of Virginia).
When you expect to make several payments to the same U.S.-based participant over the course of a year, it's common to request a W-9 at the start of the study. Other teams wait until the participant approaches the reporting threshold.
The higher threshold gives you more runway, but it also makes tracking matter more. A participant who would have triggered a W-9 request after six sessions might now take twenty, spread across multiple studies and multiple project codes. If those payments aren't aggregating in one place, it's easy to cross $2,000 without noticing.
If it's unlikely a participant will get anywhere near the threshold, some organizations advise against requesting unnecessary personal information.
What happens if you fail to collect W-9s or file 1099s?
The IRS requires you to make solicitations at the start of the business relationship and before the end of each year, and to document them as proof in case the recipient never provides a W-9 or W-8 BEN.
If a U.S. participant crosses the $2,000 threshold and doesn't submit a W-9, you may be required to apply backup withholding of 24% to their payments and report it on Form 945. The withholding trigger moved from $600 to $2,000 alongside the reporting threshold, so it now tracks the same number. One thing to watch: if you do withhold on a payment, you're required to file the 1099 even if the participant's total ends up below the threshold.
Penalties can apply per form for late or missed filings; see the IRS website for current amounts.
None of this is complicated, but it's easy to lose track of across a dozen concurrent studies. The teams that don't scramble in January are the ones that set up their form collection in advance and let it run.
Disclaimer: This overview is meant to give you the lay of the land, not replace a proper map. It pulls together the key themes and pitfalls we see around incentive-related taxes, but it doesn't cover every twist in the code or your company's specific facts. Before you rely on anything here, run it past your own tax advisors to be sure you're handling incentives in a way that's fully compliant and optimized for your situation.
Collecting forms at the right moment and keeping clean records year-round is most of the work. An incentives platform with automated W-9 collection and 1099 prep built in can help with tracking so tax season stops being a project.